Fixed or variable at renewal
What each costs, and what each means for your payments.
The fixed rate
The payment stays flat for the term. The starting rate is often higher.
The variable rate
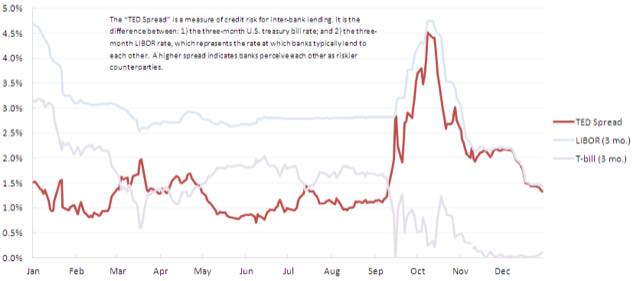
The payment follows market rates. It can rise as well as fall.
Questions to ask yourself
- How long will you hold the property
- Can you absorb a payment increase
- Do you plan to sell before the term ends
What peace of mind costs
The gap between fixed and variable is often a few tenths of a point.
On a large loan, those tenths become thousands of dollars a year.
The rental property case
Rents rise slowly. A payment that climbs fast creates a shortfall.
A fixed rate protects that margin, at the cost of a higher starting rate.
The split option
Some lenders allow splitting the loan into two portions.
What happens at the end of the term
A variable rate often converts to fixed at renewal, at no cost.
Check whether that switch is allowed mid-term.
That flexibility is sometimes worth more than a few tenths of a point.
Asking about the cap
Some variable loans cap the payment increase.
Others let the payment follow the market fully.
Ask for that detail before choosing variable.