Loan nearing maturity
Upcoming maturity and time to compare offers.
The partner broker calculates repayment of the current loans before comparing new terms.
Book a callUpcoming maturity and time to compare offers.
Available equity for an acquisition or renovations.
Several debts combined into one loan.
Updated value and income after renovations.
Ownership buyout without selling the property.
The lender reviews the balance, rate, maturity and applicable penalties.
The accepted value and net income determine how much can be refinanced.
Existing debt, penalties, fees and reserves are deducted from the new loan.
Renovations, acquisitions, consolidation or buyouts require a clear use of funds.
The owner’s estimate may differ from the value accepted by the lender.
The penalty, discharge and other fees reduce the funds available.
More debt or a higher rate increases the payments.
The lender needs the requested amount and a clear use of funds.
Value and payment capacity both limit the amount.
Debt, penalties, fees and reserves are deducted.
The term must fit the expected hold and next maturity.
The lender sets the rate based on risk, amount and collateral.
| Loan type | When this loan type may apply |
|---|---|
| Conventional refinancing | A new loan based on current income, value and property history. |
| Refinancing with available funds | The new loan repays current debt and leaves funds available. |
| Debt consolidation | Several debts are combined under real-estate collateral and one payment schedule. |
| Temporary loan before refinancing | A short-term loan before renovations, a sale or refinancing. |
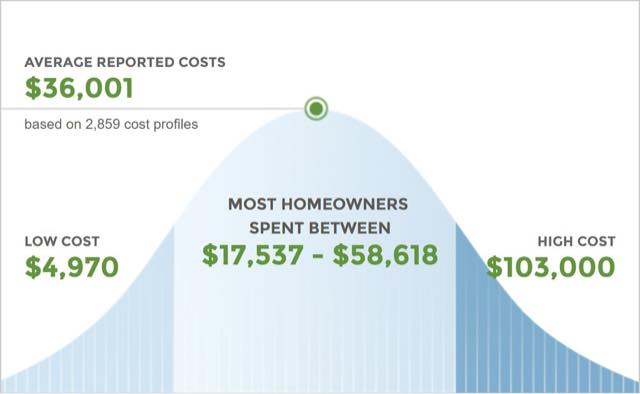
Value, current debt, available amount and use of funds.
How it is calculated and when paying it makes sense.
Renewal window, preparation and room to negotiate.
Combining loans: terms, security and effects on flexibility.
Invoices, new value, revised rents and waiting period.
What each costs, and what each means for your payments.
Start before maturity to obtain documents, an appraisal and several offers.
The lender considers value, net income, current debt and costs.
Not necessarily. Compare it with savings, available funds and the cost of waiting.
The lender reviews leases, expenses and income history.
Yes, when value, mortgage positions and income support the new loan.
The lender may require one to confirm the value used.
Balances, income, estimated value and intended use of funds.
Book a call