GuidesCommercial
Mixed-use: what lenders review
Residential share, commercial share, leases and zoning.
Square metres for each use
Income from each part
Municipal zoning and permitted uses
How the space splits
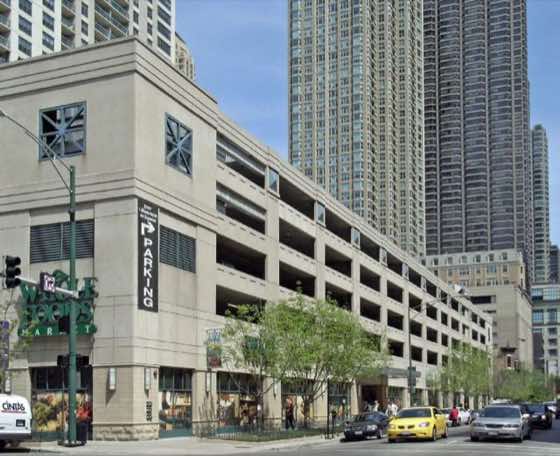
The lender separates residential from commercial space. Each part follows its own rules.
- Square metres for each use
- Income from each part
- Municipal zoning and permitted uses
- Ground-floor commercial leases
The threshold that changes everything
Residential financing carries better terms than commercial.
Many lenders treat the request as commercial once the commercial share passes twenty per cent of the floor area or the income.
The exact threshold varies by lender: ask for theirs before applying.
Uses that concern a lender
- A restaurant, for fire risk
- A garage or dry cleaner, for contamination
- A highly specialized business, hard to re-let
- A unit vacant for several months
What else to prepare
Provide the location certificate and zoning confirmation. They settle doubts about permitted uses.
Insuring a mixed-use building
The commercial portion raises the premium, sometimes sharply.
Get a quote before setting your operating budget.
An insurer that refuses the risk also blocks the financing.